Eligibility
The $16,000 ceiling is averaged, not current.
One bonus month can close the EC door for a year.
For HDB upgraders & EC applicants
Most families find out what they could actually afford after they have already committed. You are going to find out first, in writing, in 45 minutes.
Free · No obligation · Your numbers back within 24 hours
Isaac Lee · PropNex Realty · CEA R043955C. Figures indicative.
Eligibility
The $16,000 ceiling is averaged, not current.
One bonus month can close the EC door for a year.
Sequencing
Sell first or buy first is a money decision.
Get it backwards and you pay the extra stamp duty, or a year of rent.
CPF
The CPF you pay back is bigger than you think.
Everyone remembers the CPF they took out. Almost nobody counts the interest on top.
Timing
Your 5-year wait and the launch dates rarely line up.
The gap is where families get forced into a bad decision.
Exit
Your buyer pool matters more than your view.
The unit line you pick, and its size, decide what you get back later.
The answer
Sometimes the correct move is not yet.
You will get that in writing too, with the reason.
The expensive part
Nobody loses money on a Singapore home because they paid twenty thousand too much. They lose it because they sold before they were cleared to buy, or bought before the income averaging was checked, or signed an option while the CPF refund was still a guess. Every one of those is an order-of-steps mistake, and every one of them can be avoided in a single sitting, before there is anything to regret.
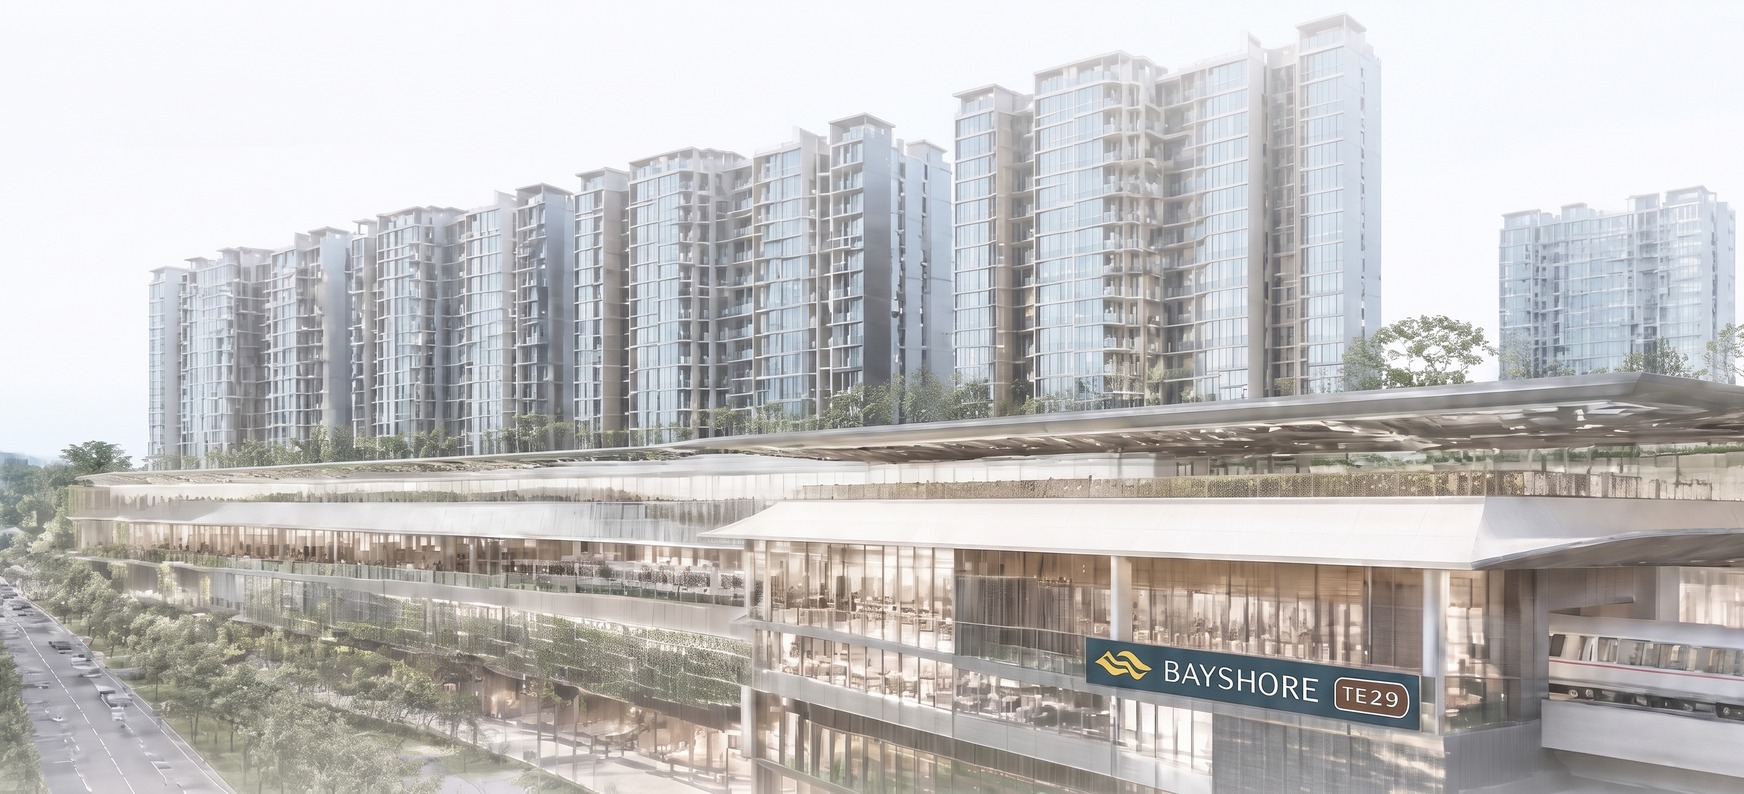
Two routes, two sets of rules. Only one of them is open to you today.
Not sure which of the two is open to you? Eight questions will tell you.
Two versions of the same year
“Can we even afford to move?”
Before the numbers are checked
Every conversation ends the same way. We’ll look at it again next year. Nobody has told you it’s impossible. Nobody has told you it’s possible either.
Waiting isn’t free. The CPF you owe yourself keeps growing against your sale money, and your 5-year clock keeps ticking.
“We knew the number before we moved.”
After the numbers are checked
Same household. Same salary. Same flat. The only thing that changed is that somebody sat down and worked out what was actually true.
Their real budget turned out to be $1.58M, not the $1.10M they assumed. That is $480,000 they could have used all along.
Most people don’t lose the upgrade to a bad decision. They lose it to a year of not deciding.
Find out your own number instead of guessing at it. Free, and back within 24 hours.
Illustrative figures representing a pattern seen repeatedly, not any one client's actual numbers. Every position differs and is subject to prevailing regulations, valuation and your own due diligence.
How it runs
Step one · Baseline audit
Your real position, checked. Not guessed.
The CPF you must put back with interest, the 55% cap on all your loans, the 30% cap on an HDB or EC home loan, your cash, and what your flat will really leave you with. Plus how HDB averages your income and your 5-year dates. You leave with one page saying what you can afford, and what would break it.
Step two · Tailored shortlist
Picked for how easily you can sell it later.
How many buyers there will be for that unit line and size when you sell, not just how it looks today. And how much of the floor area you are paying for is space you will actually use. Three to five options survive, each with the reason for it and the reason against it.
Step three · End-to-end execution
From balloting through to keys.
Application and ballot day, picking your unit, signing the option, the loan, timing the sale of your flat, then completion and keys. Run in order by the same person who worked out your budget, so no month arrives where you own two homes, or none.
That is the whole process. Want to see what it looks like with your numbers in it?
Who runs it
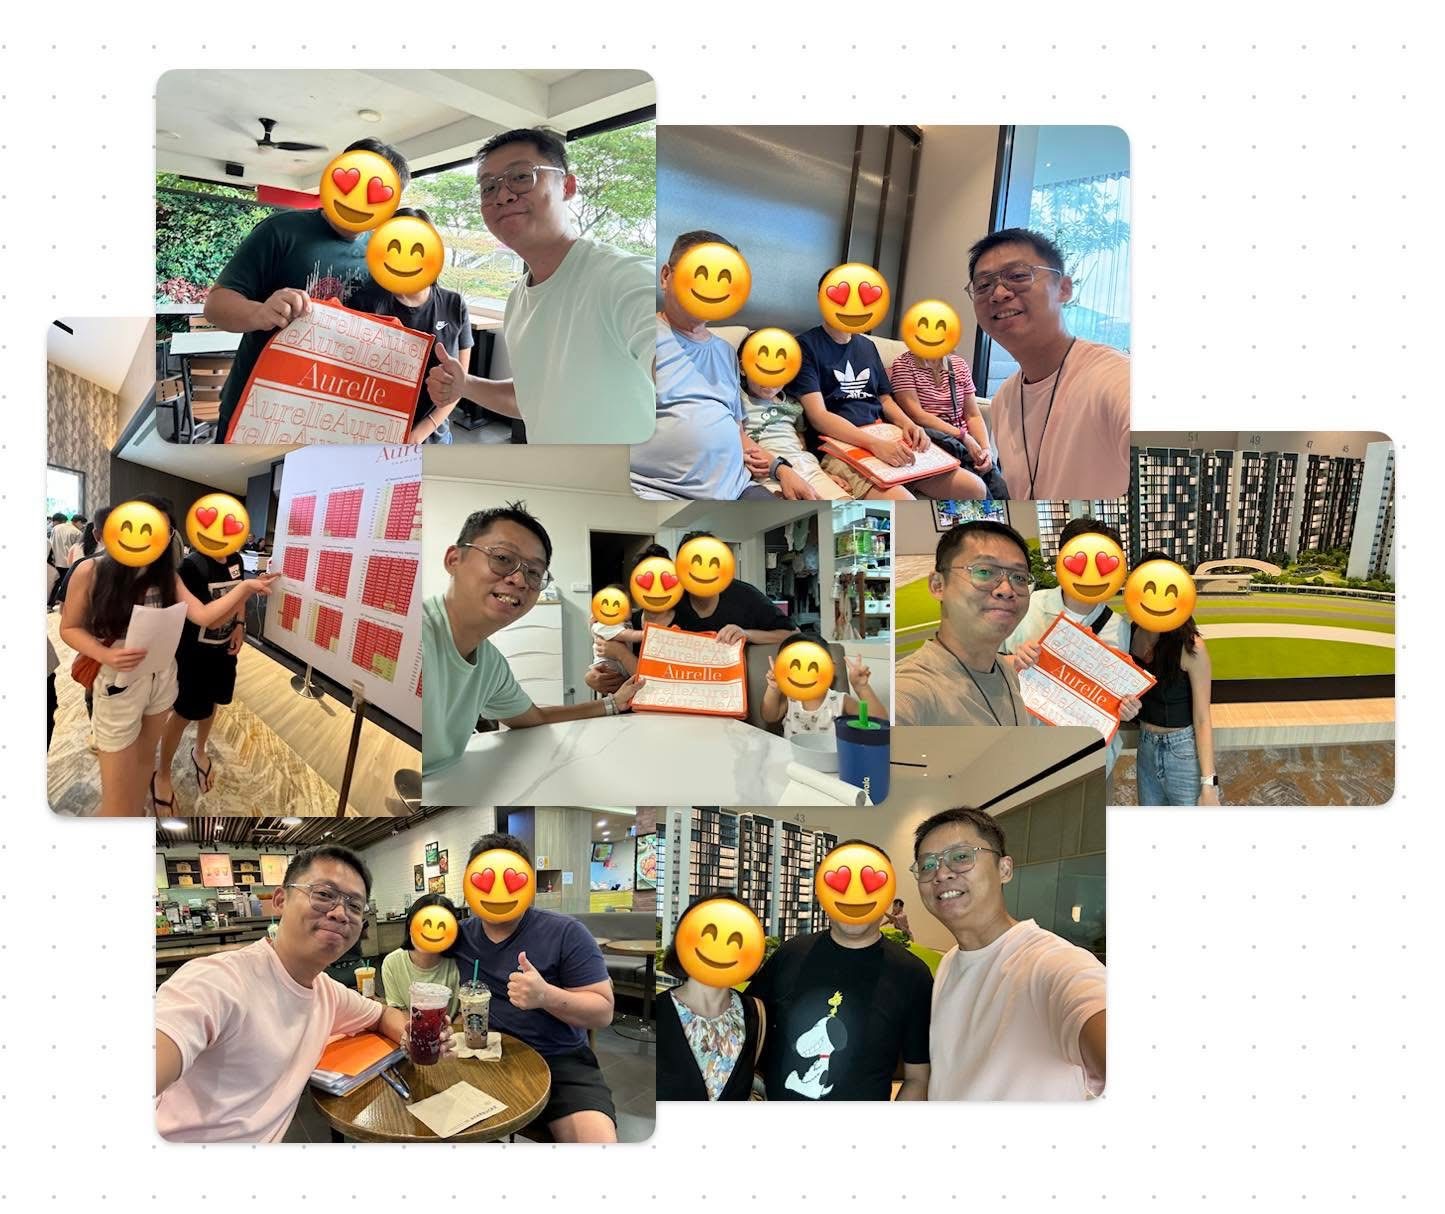
I am not a generalist. I do not chase listings across the island, and I turn down more work than I take. There is one thing I do properly: establish the ceiling a family can genuinely carry, then run the move that follows from it.
Fifteen years in this market, and the last stretch of it narrowed almost entirely to two situations. HDB owners upgrading once their 5-year stay is up, and families working out whether the EC route is still open to them. Both come down to the same few sums: the CPF you must put back with interest, the 55% cap on all your loan payments, the 30% cap on a home loan for an EC or HDB flat, your income averaged the way HDB actually averages it, and the order in which you sell and buy. Get that order wrong and it costs more than any negotiation will ever recover.
A real share of the families I sit with are told to wait, and some are told to stay exactly where they are. That costs me a transaction today. It is also the only reason the advice is worth anything to you.
More than 150 families have been through this. The same person works out your numbers, filters your shortlist and sits with you through completion. You are never passed to a team member halfway through, and no month arrives where you own two homes, or none.
The method
Six numbers, run in the same order every time, settled in writing before you view a single unit. Not a calculator guess. The real limits, in your real situation.
That is the method. Run it on your own flat and see what it says.
YouTube viewer → client
“We came across Isaac’s YouTube channel while randomly looking into upgrading. One video turned into a few more, and before we knew it, we were chatting with him directly. From the start, he kept things real, clear about how the EC process works, the timelines, and especially the financing part, which is honestly where most people get stuck. It wasn’t a sales pitch, more like a proper reality check, in a good way.
Our first visit was to North Gaia. He showed us the layouts, ran through the numbers, nothing pushy, no fluff. We didn’t go ahead back then. We had other things going on with family. But when Aurelle came around, we were ready. Because of the earlier prep, we already knew our options, had financing sorted, and felt a lot more confident. Ended up getting a unit.
Start to finish, Isaac gave us space, was upfront and open, and made the whole thing feel less stressful than it could’ve been.”
“Isaac is one of the most knowledgeable and sincere property agents I have come across. Unlike most agents, he doesn’t solely focus on getting the deal done but is willing to spend time to educate us on the general property market and provide an honest assessment of whether buying into an EC is a right decision for us. He provides good insights and financial estimates for us to be equipped to make an informed decision, and at no point is pushy on us to commit to the deal. Would definitely recommend to reach out to him if you are looking into the EC market.”
“Isaac is a very dedicated and sincere agent. It is our first time buying a property and it was a seamless process due to Isaac’s extensive experience and guidance. He is very knowledgeable about the property market in Singapore and had offered us his valuable insights in unit and stack selection. He even brought us to various showflats to give us an overview of other projects so that we can make an informed decision. Most would think that purchasing an EC is a daunting process, but Isaac ensured that it was stress-free and smooth sailing.”
Written by clients, reproduced as sent. Full messages available on request.
Rather just ask one question first? Message Isaac directly.
WhatsApp IsaacVersatility
The CPF you owe back, what is left on your loan, and what your flat actually values at decide how much money reaches your hands on completion day. We work out that figure first, then work backwards to your budget, so the sale and the purchase are planned together instead of hoped into place.
Grants, BTO versus resale versus EC, and the loan ceiling that actually binds you. The choice you make at 30 decides how much you own at 50, so it is worth 45 minutes on the numbers before a weekend at showflats.
The $16,000 income limit is based on your average monthly pay over a year, not this month, and your home loan is capped at 30% of it. A raise, a bonus or a job change can shut the door. We check whether the route is open, and for how long, before you fall in love with a floor plan.
Whose name the home is in, whether you take one name off, and the refund deadline all pull against each other, and the wrong order can cost six figures. We put the options side by side with real numbers, including the one where the honest answer is that a second property is not worth it for you.
What gets checked
Nothing here is guessed. Every line gets checked against your actual papers.
What has to go back into your CPF when you sell, and what is genuinely yours in cash afterwards. Worked out, not guessed.
All your monthly loan payments together cannot pass 55% of your income. Car loan, renovation loan, personal loan, and anything you guaranteed for someone else all count.
For an EC or HDB purchase, the home loan alone cannot pass 30% of your income. This one usually bites first.
HDB averages your household pay over 12 months, not this month, and that includes the bonus you forgot about.
When you are allowed to sell, when you are allowed to apply, and what you are shut out of today.
The figure after the loan is repaid, CPF is returned, and commission and legal fees are paid. That is the money that funds the next home.
The months between selling and collecting keys, and exactly how that gap gets funded without panic.
When buying first triggers it, what it costs you up front, and how long you have to sell to get it back.
Valuation comes in under offer. Sale takes three months longer. Rates move. What breaks first, and what to do about it.
All nine of these get checked for you, free, and you get the answers back within 24 hours.
What you actually walk away with
Not a brochure. Not a "let's grab coffee". Six things you keep, whether you transact with me, with someone else, or not at all.
The highest price your income, CPF and current loans actually support, written down with every step shown, so you can check the maths yourself.
Whether the EC route is open to you, and the specific date or event that closes it. The difference between applying this cycle and waiting a year.
Both orders priced side by side: extra stamp duty, months of rent, the cost of a short-term loan, and CPF sitting idle. So you choose the order on numbers, not nerves.
Picked for how easily you can sell later and how much of the space you will actually use. Every option comes with the reason for it and the reason against it, because only one of those is usually offered.
What happens if valuation misses, if the sale runs three months long, if rates move against you. The failure points named in advance, while they are still cheap to fix.
Ballot day, picking your unit, signing the option, submitting the loan, timing the sale, completion and keys. You are never passed to a junior halfway through.
You pay nothing. You commit to nothing. There is no viewing booked at the end, and nobody chases you afterwards. If the honest answer is that you should wait, or that you should not move at all, you get that in writing, with the reason, and the workings are yours to keep either way. The only way this costs you anything is if you never find out where you stand.
Currently tracking
Two Executive Condominiums and one private launch. Each has a different set of rules and a different reason to move early.
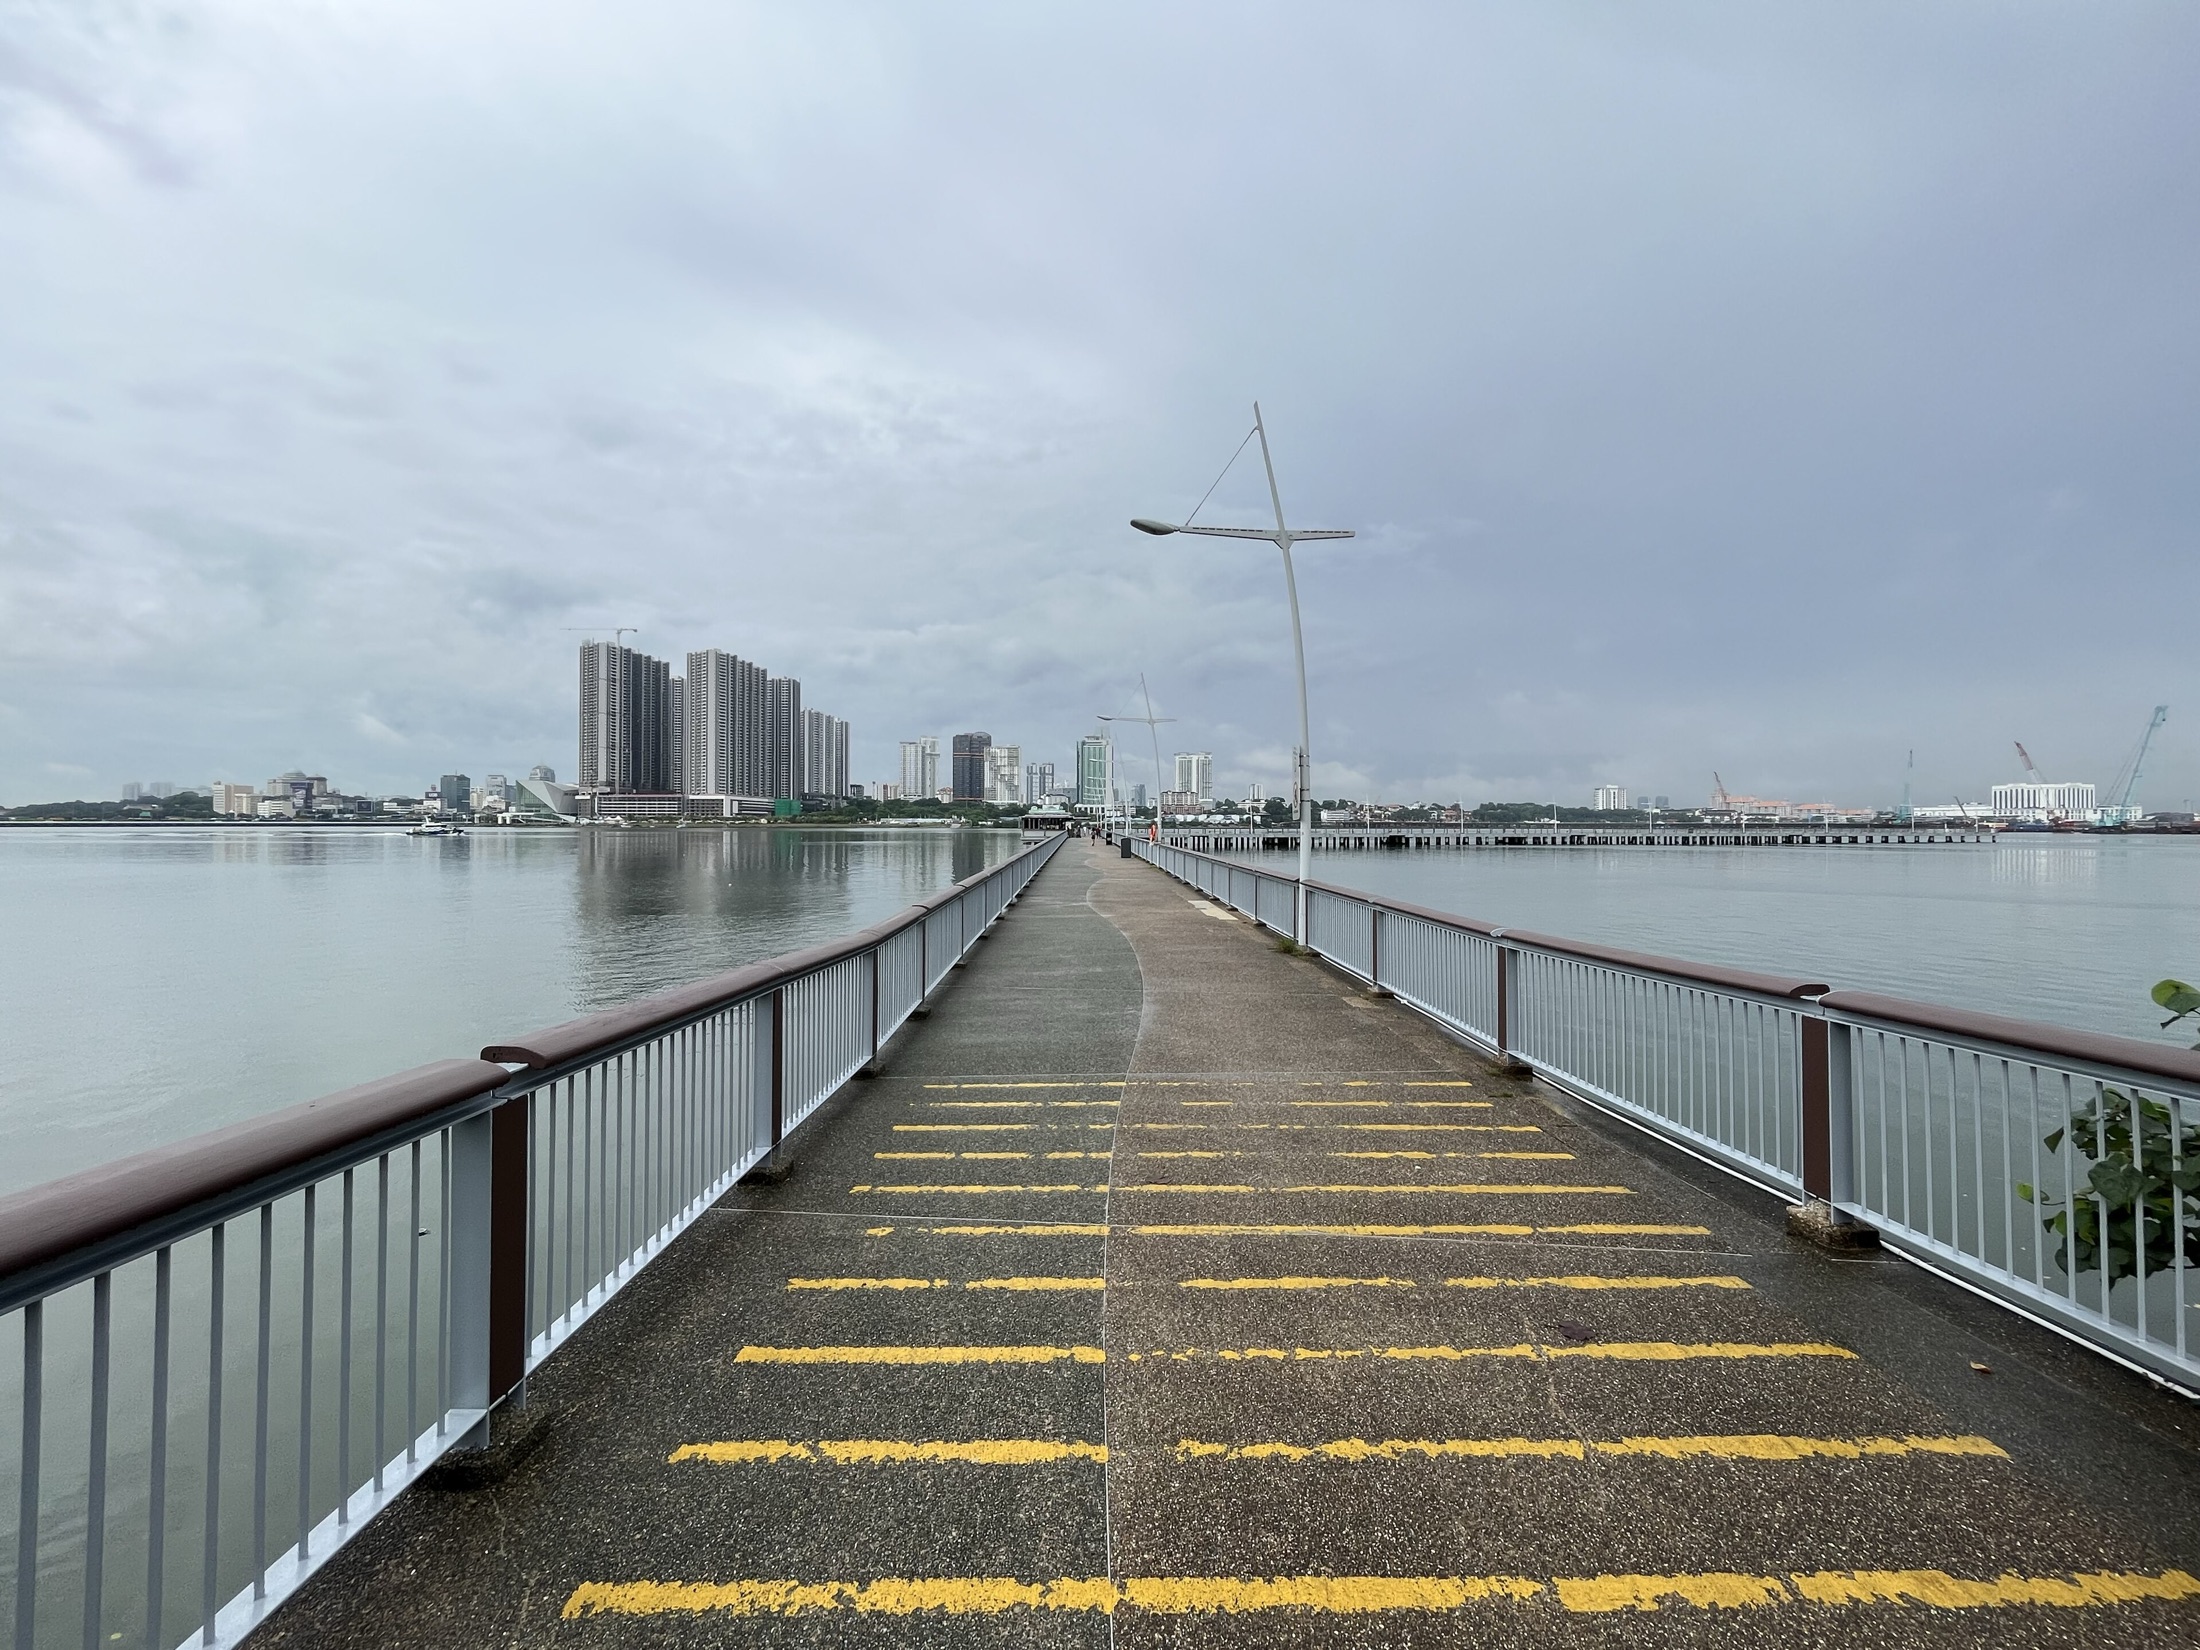
First Woodlands EC in 10 years
Woodlands Drive 17 · D25 · CDL
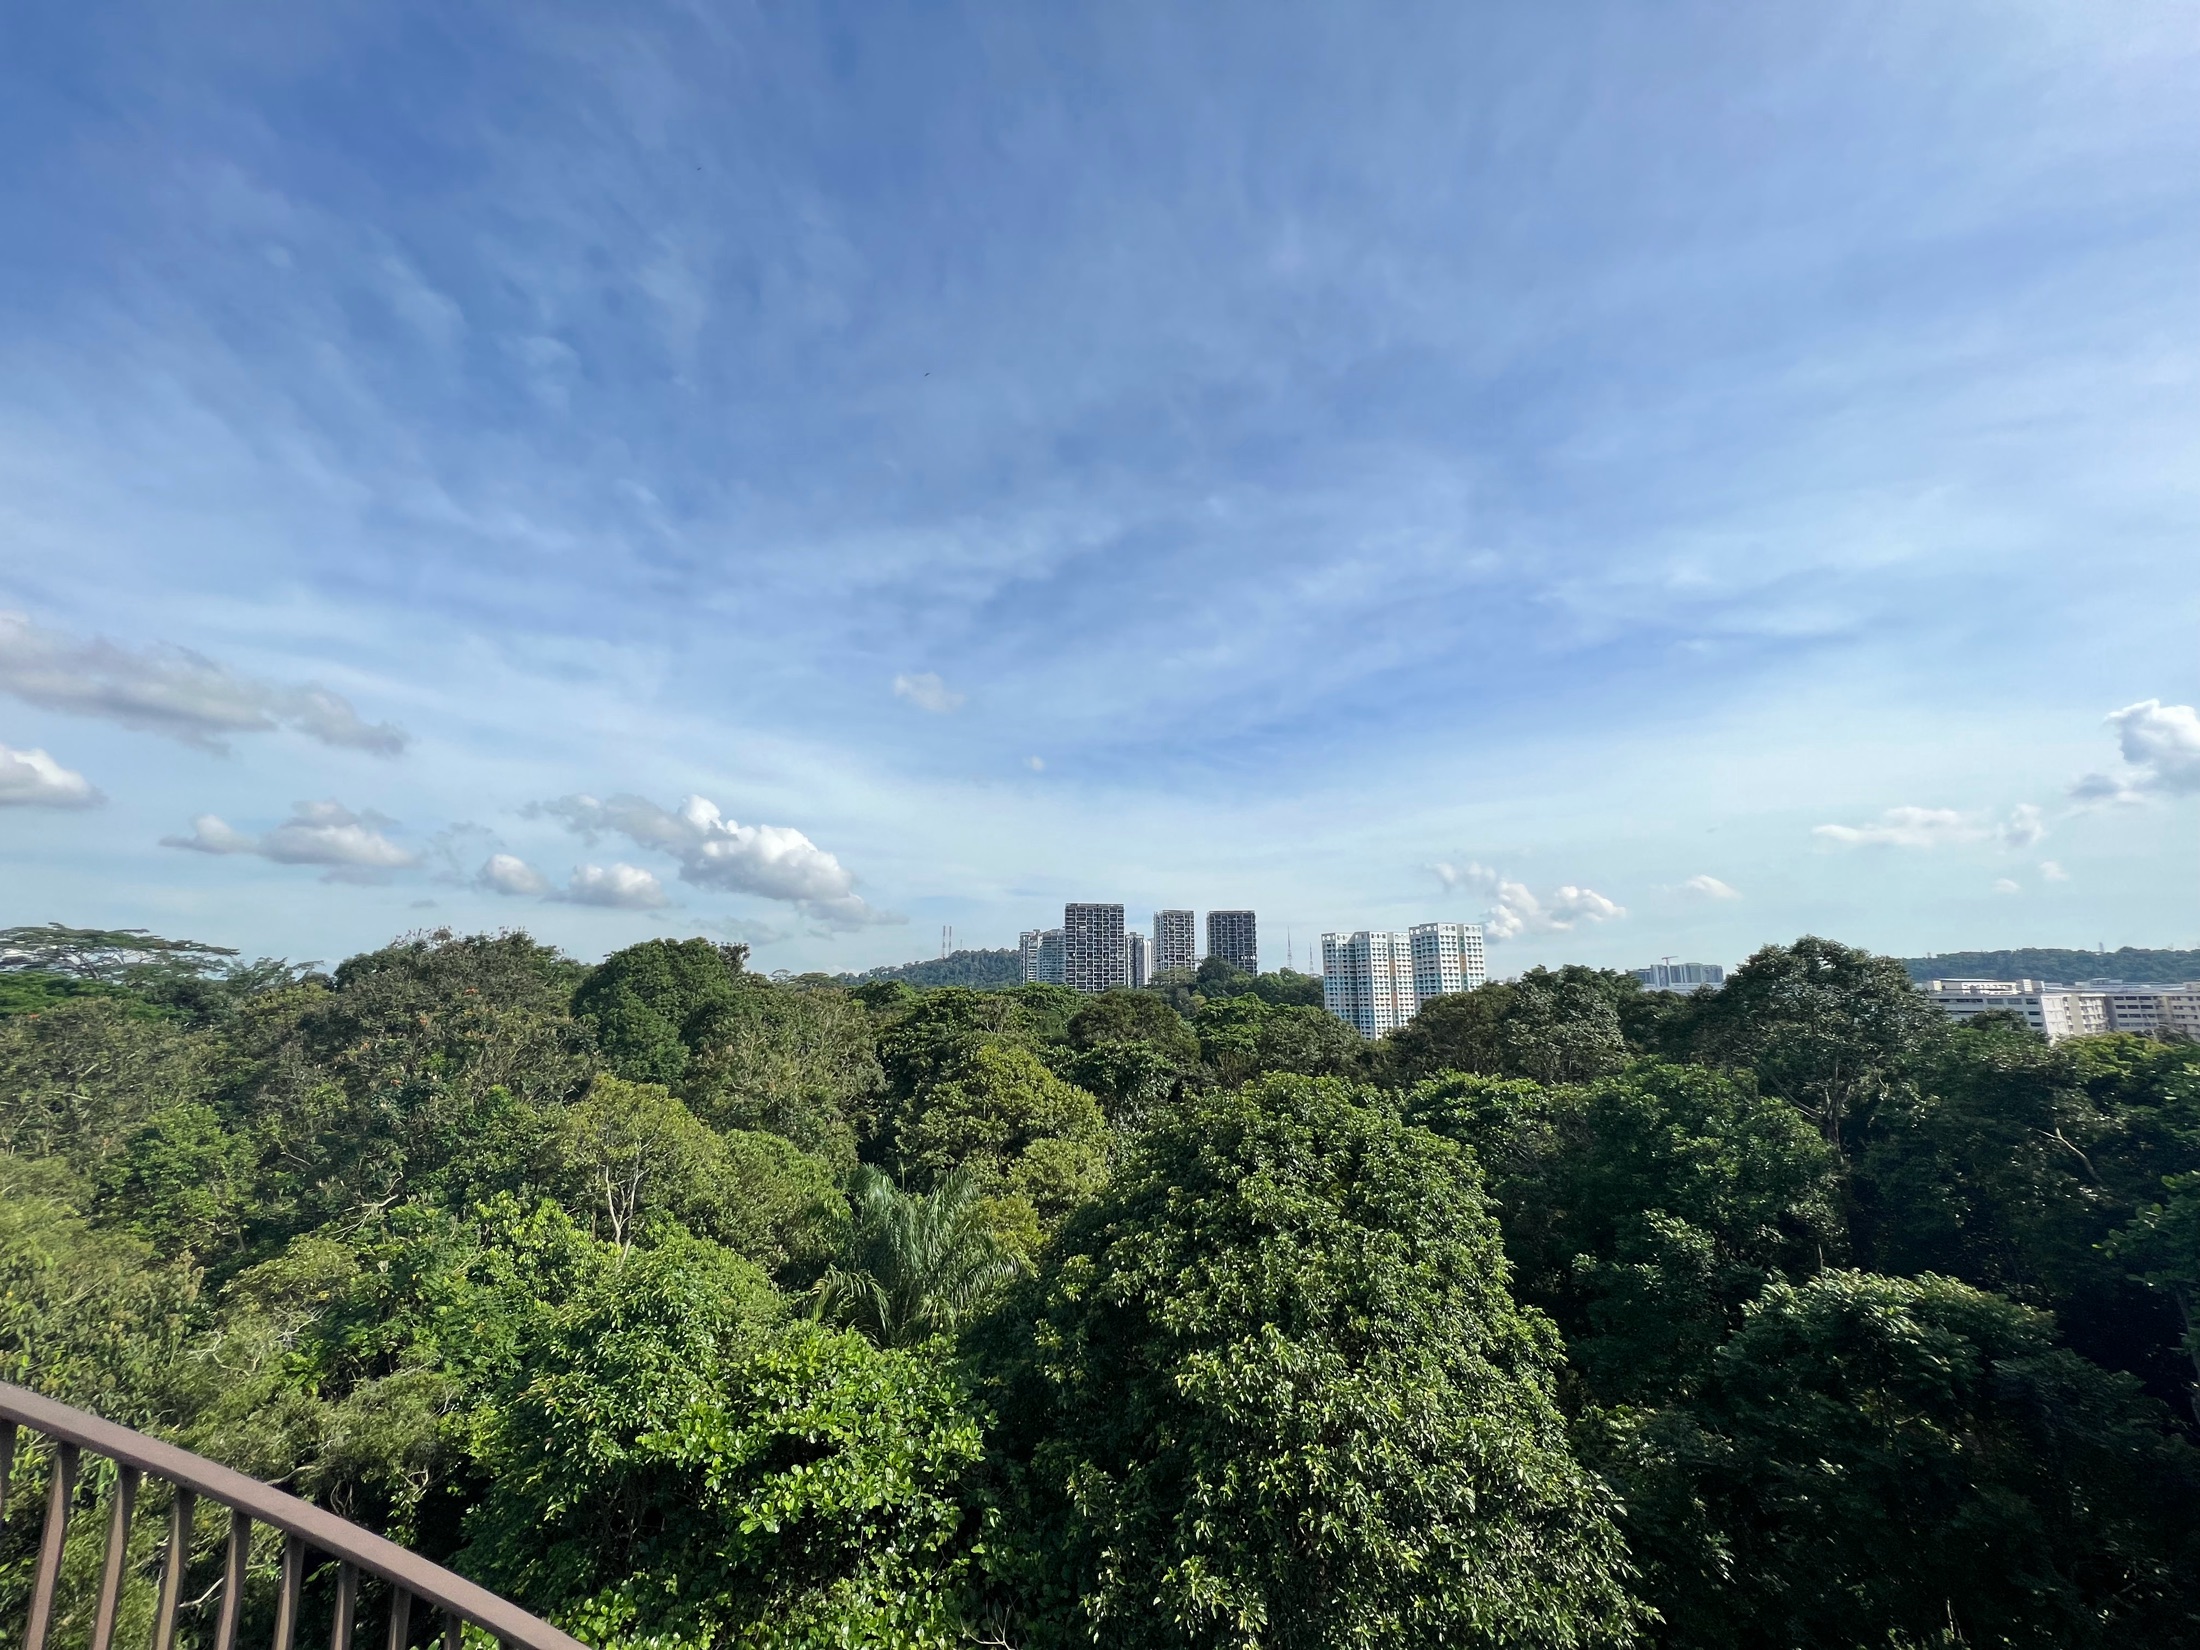
First Bukit Panjang EC in 15 years
Senja Close · D23 · CDL
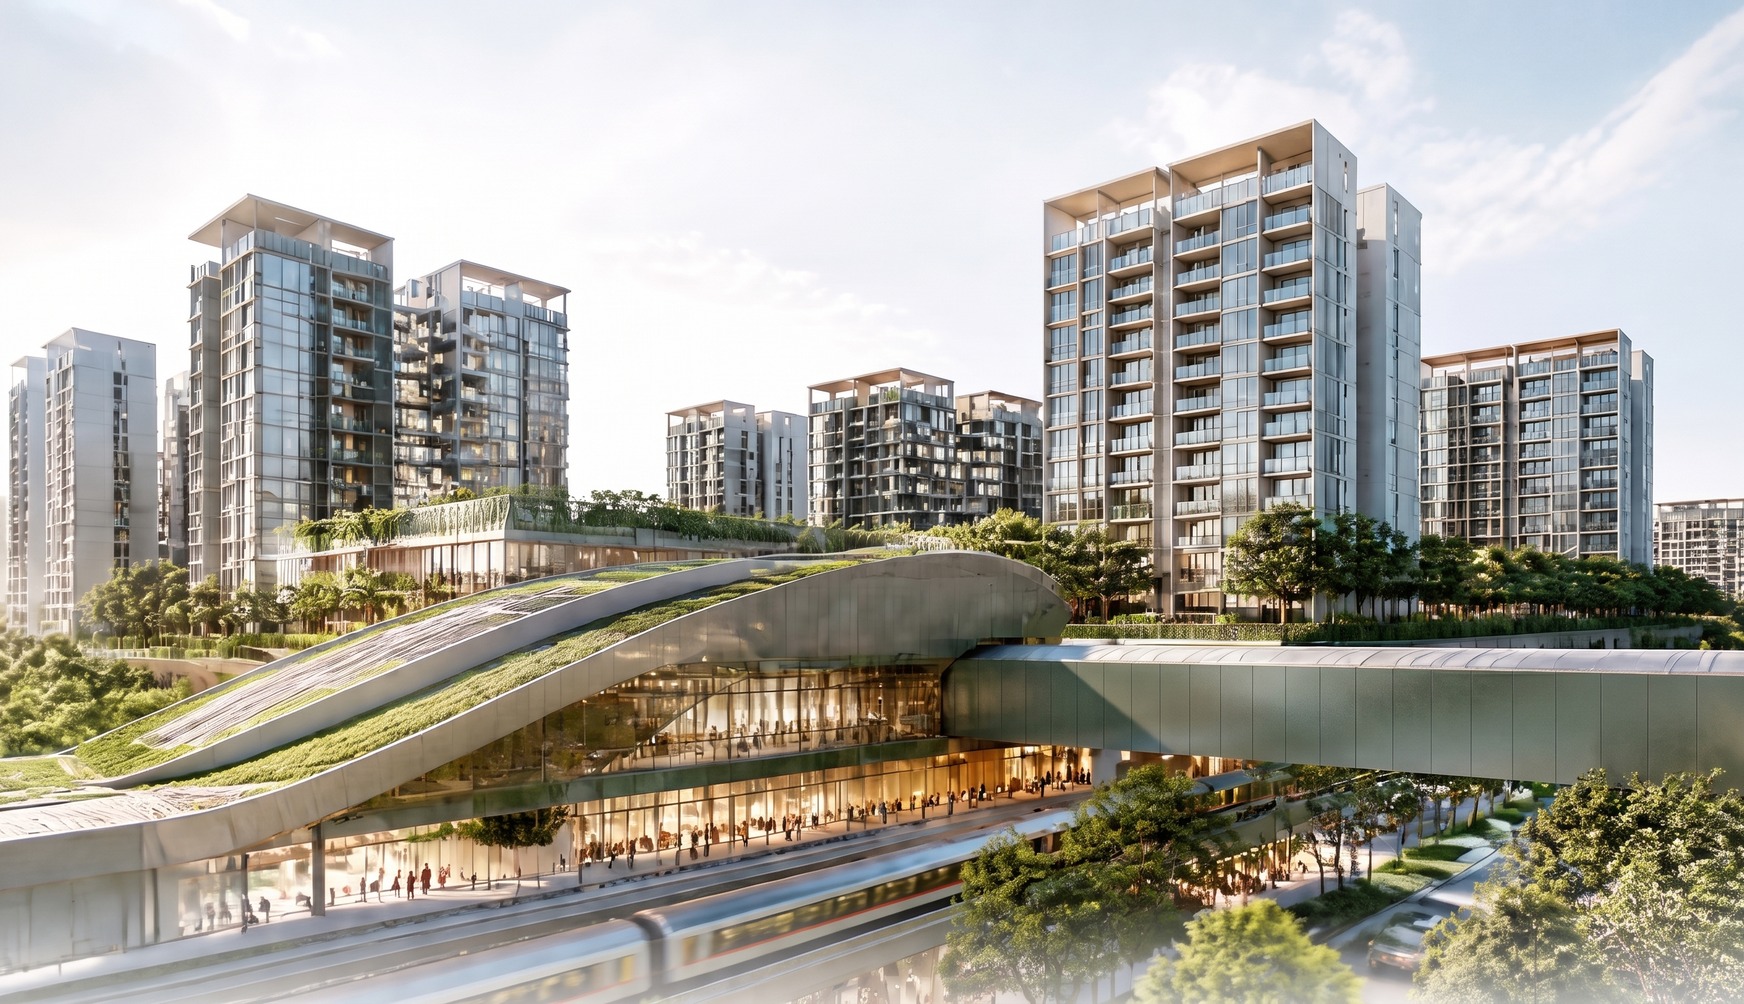
Price guide out before doors open
Upper Thomson · D20 · UOL, SingLand, CapitaLand
Want to know which of these three you could actually buy into? That is the first thing the check tells you.
Unit counts and preview windows are indicative and subject to the developers' announcements and approval of sale.
Still have a question that is not here? Ask Isaac directly, no form needed.
WhatsApp Isaac
2-minute property check
Answer a few short questions. I come back within 24 hours with the price ceiling your income and CPF genuinely support, whether the EC route is open to you and until when, and the single thing to settle before you view anything.
Rather skip the questions? and I will ask them myself.
Launch dates, EC ballot results, price movements in the estates I track, and the occasional blunt note on a project I would not buy. No brochures, no chasing. Leave the moment it stops being useful.