New Launch · Singapore Property Planning
98.3% of New-Launch Subsales Made Money. What the 76 Losers Say About Which Condo to Buy
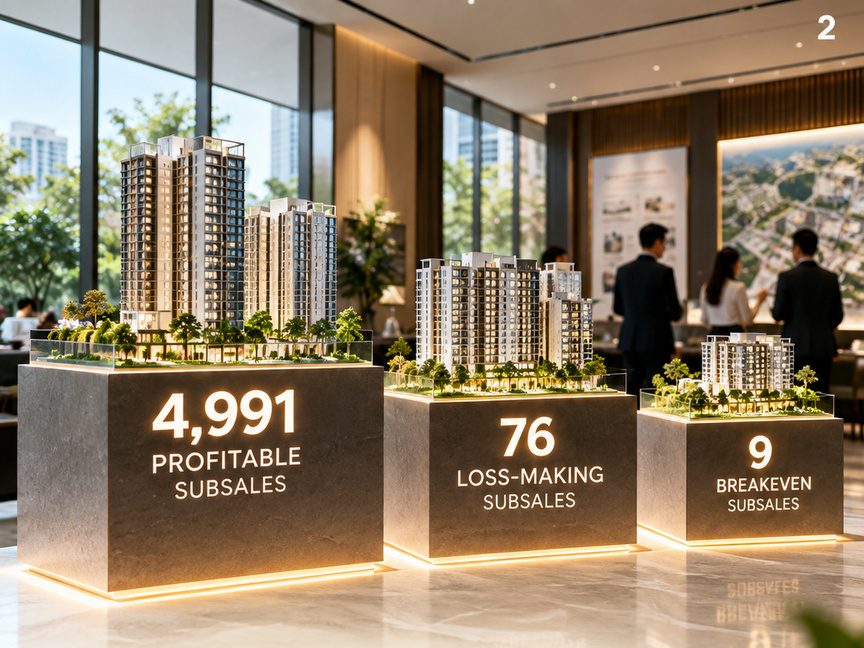
Out of 5,067 private condo subsales since 2021, only 76 lost money. That is a reassuring headline and a useless buying guide. The losers are where the information is, and they were not random.
 Isaac Lee · PropNex Realty · Updated Oct 2026
When I read that 98.3% of new-launch subsales made money, my first reaction was not relief. It was curiosity about the other 1.7%. If you are about to put down a booking fee, the average result matters far less than the conditions under which people lost.
What a subsale actually is
A subsale is when someone buys a unit directly from the developer and sells it on before the project receives its certificate of statutory completion. They skip the wait, and they usually pay Seller’s Stamp Duty for the privilege if they sell within the holding period. Because the seller bought at launch pricing and is selling into a market that has moved, subsales are one of the cleaner tests of whether a launch price held up.
The figures here come from an EdgeProp analysis of URA Realis data published on 24 September 2026, covering private condo subsales between January 2021 and August 2026. I have not rerun the data myself, so treat the numbers as EdgeProp’s.
The numbers, laid out plainly
A quick note on the 1.7% in the headline: it is the 76 losses plus the 9 breakevens, so about 1.7% of sellers did not make money, and 1.5% lost it outright.
The median loss of 4.3% is the number I would keep. These were mostly not catastrophic outcomes. They were people who paid a full price at launch, sold into competition, and gave back a few percent. The exception is the tail, which we will get to.
Where the losses sat: the CCR was the outlier
Loss rates were uneven across regions. About 7.1% of Core Central Region subsales lost money, against 1.9% in the Rest of Central Region and 0.7% in the Outside Central Region.
I read that as a story about buffer, not about location quality. Prime-district launches are priced with the least slack. When the entry price already carries the best-case view of the next five years, a seller who needs out early has nothing to absorb a flat market or a rival launch next door. Outside the central region, entry prices are lower, the buyer pool of families and upgraders is deeper, and that same seller usually has room to move.
The market did not punish locations. It punished entry prices with no room left in them.
Two projects, one in five losses
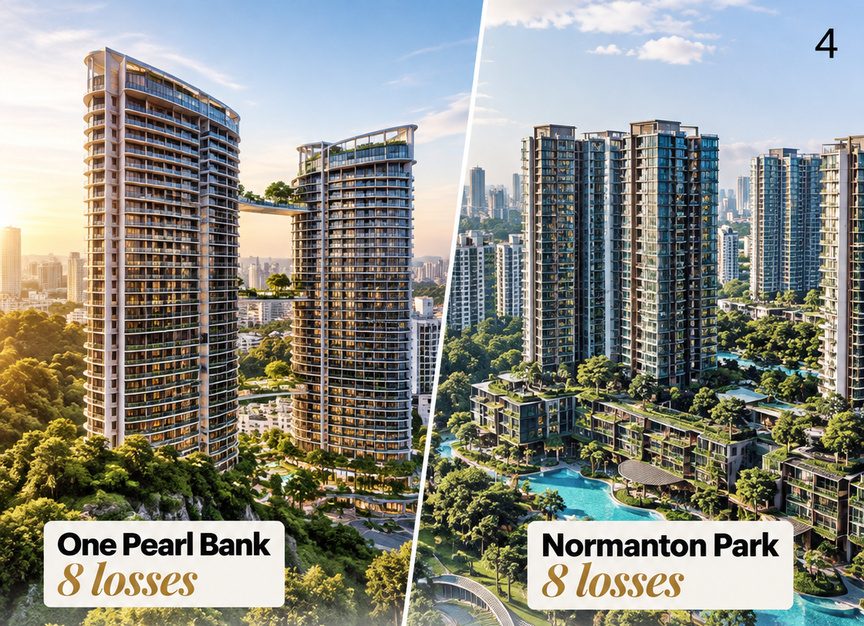
Two projects, both in the Rest of Central Region, accounted for 16 of the 76 losses. That is roughly one in five.
- One Pearl Bank (774 units): 57 subsales, 8 losses, a 14% loss rate. The largest single loss was about $1.1 million, around 13% below the purchase price.
- Normanton Park (1,862 units): 207 subsales, 8 losses, a 4% loss rate. The largest loss was about $83,000, or 8% below purchase price.
The two look nothing alike. One is a high-priced, tall, relatively small development. The other is one of the largest condos launched in the area, with a long sales period. So whatever the common thread is, it is not size of project or even price point alone. It is something about what the buyers were holding.
The common thread: compact units
At Normanton Park, 7 of the 8 losses were units under 600 sq ft. EdgeProp’s figures put the loss rate for that size band at about 23%, against under 1% for larger units in the same project.
I would not turn one project into a law. But I would test it on any compact unit I was shown. Small units tend to launch at a higher psf, the total quantum looks affordable, and the pitch is investor-friendly. The catch shows up on exit. You are selling into a thinner pool, because only certain buyers want a one-bedder, and you are competing directly against the unsold and resale stock of the same layout in the same building.
Do not just ask whether you can buy it. Ask whether the next buyer will want it too.
Why compact units struggled.
Three forces stack on top of each other, and these are my reading of the data, not something the dataset measured directly:
- A higher psf at entry. The smaller the unit, the more the psf stretches to hold the quantum down. You start with less cushion.
- A thinner pool of resale buyers. Fewer owner-occupiers want to live in a compact unit long term, so you rely more on investors and singles.
- Direct competition. A big project has many near-identical units. When one owner needs to sell, so do several others, and the cheapest listing sets the price.
Should you avoid small units completely?
No, and I would be wary of anyone who says yes. The lesson from this data is not that small is bad. It is that bad entries get exposed later.
A compact unit is more sensible when the entry price is genuinely right, when future supply nearby is limited, and when you are buying for your own use or for a clear niche buyer, such as someone who wants to be near a specific school or MRT line. It is riskier when you are paying the peak psf of a launch weekend, when there are many similar units in the building and the catchment, and when your plan depends on easy appreciation covering the entry premium.
What I would stress-test before committing
Run four checks before you pay a booking fee. They take an evening.
- Entry price. Pull the last twelve months of caveats from URA’s residential transaction search for comparable nearby projects, filter by unit size band, and take the median psf. Then ask how far above that the launch price sits and what justifies the gap. I wrote more on this in the Sin Ming land bid piece.
- Future supply nearby. Count the sites in the government land sale pipeline and the launches due in your exit window within the same catchment.
- Buyer pool at resale. Is there a real owner-occupier market for this layout, or only investors?
- Exit competition. When you sell, what will you be listed against, in your own building and next door?
Early-bird access and priority queues are separate topics, but they interact with this. If you are being rushed to a decision, how the VIP queue actually works is worth reading first.
A caution on what this data cannot tell you
The window covers a market that mostly rose. A 98.3% success rate is a statement about 2021 to 2026, and a buyer who enters at a peak into a flat or falling market faces different odds. The data also only counts people who sold. Owners who held on because the number would have hurt are not in it. So I read this as evidence of where risk concentrates, not as a guarantee that the rest is safe.
Buy for the next buyer
The habit I want every buyer to build is a simple one. Before you commit, imagine the listing you will write in five years. Who reads it, what do they compare it to, and what does your unit have that the others do not? If you can answer that clearly, the entry price usually takes care of itself. If you cannot, you are not buying a home yet, you are buying a headline.
Sources: EdgeProp Singapore analysis of URA Realis data, “98.3% of all subsale transactions made money. Here’s what we learnt from the other 1.7% that did not,” by Ng Ming Yang, 24 September 2026 (via Yahoo News Singapore). Figures are as reported by EdgeProp and cover private condo subsales from January 2021 to August 2026.
Frequently Asked Questions
Do most new-launch condo buyers make money when they sell before completion?
Yes. In EdgeProp's analysis of URA Realis data for January 2021 to August 2026, 4,991 of 5,067 subsales (98.3%) were profitable after adjusting for Seller's Stamp Duty. 76 (1.5%) lost money and 9 (0.2%) broke even. The sample covers a period of rising prices, so it describes that market and is not a promise for the next one.
Which region had the most loss-making subsales?
The Core Central Region. About 7.1% of CCR subsales lost money, against 1.9% in the Rest of Central Region and 0.7% in the Outside Central Region. Higher entry prices leave a thinner buffer when a seller has to price against similar new stock.
Are small condo units riskier to buy?
In this data set, the losses leaned that way. At Normanton Park, 7 of the 8 losses were units under 600 sq ft, a loss rate of about 23% for that size band versus under 1% for larger units. That is one project's pattern, not a rule, but it is the pattern to test before buying a compact unit at a premium psf.
What is a subsale, and how is it different from a resale?
A subsale is when a buyer sells a unit bought directly from the developer before the project has received its certificate of statutory completion. A resale is a sale of a completed home. Subsales skip the wait for completion and carry Seller's Stamp Duty if sold within the holding period.
Should I avoid small units altogether?
No. A small unit can make sense when the entry price is right, nearby supply is limited and you are buying for your own use or a clear niche buyer. The risk is a peak-psf entry with many similar units competing when you sell.
Not sure your shortlisted unit passes the exit test?
Send me the project and unit type. I will pull the transacted psf and the competing supply so you can stress-test entry price and exit strategy before you commit.
Usually replies within the day · Isaac Lee, PropNex Realty